Feature · 11 November 2026
Electronic parts prices climb faster than Taiwan's factory-gate average
For companies that source chips, memory and circuit boards from Taiwan, official price data, the makers' own revenue and distributors' lead-time reports all point the same way.
Purchasing departments have seen it on their quotes, and now Taiwan's official statistics show it. In the latest reading, the producer price index for electronic parts and components stood 23.96% above a year earlier, against 19.66% for producer prices as a whole, the Directorate-General of Budget, Accounting and Statistics (DGBAS) said. Its index for computers, electronic and optical products rose 37.82%. 2
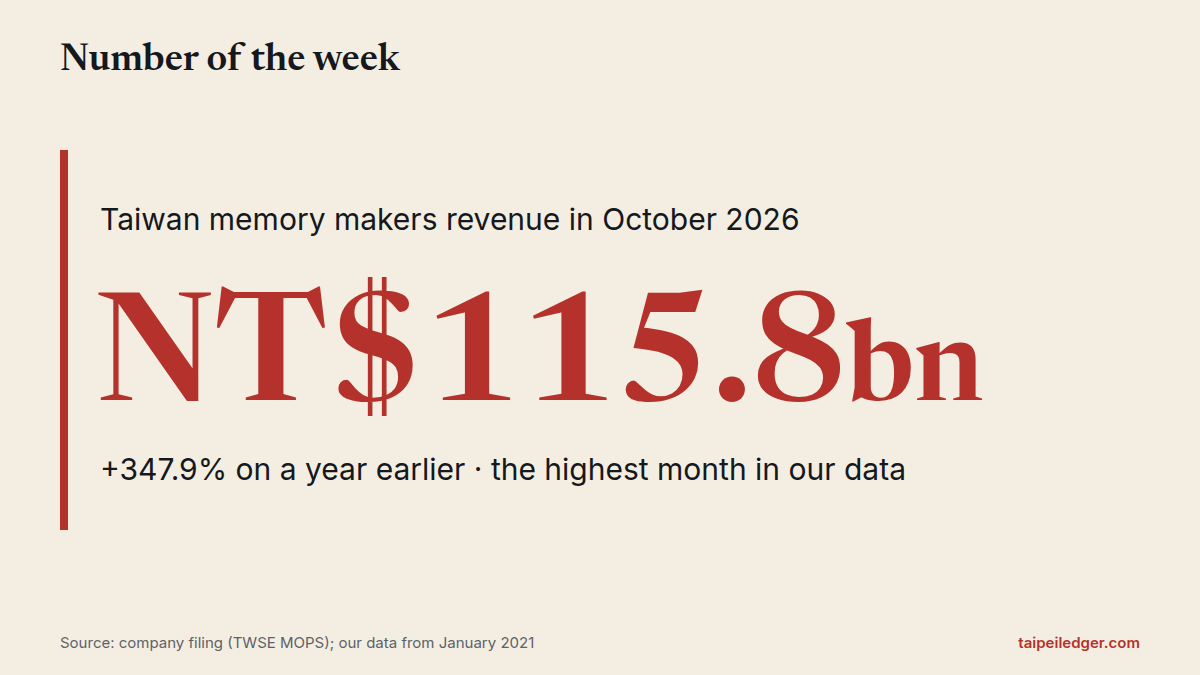
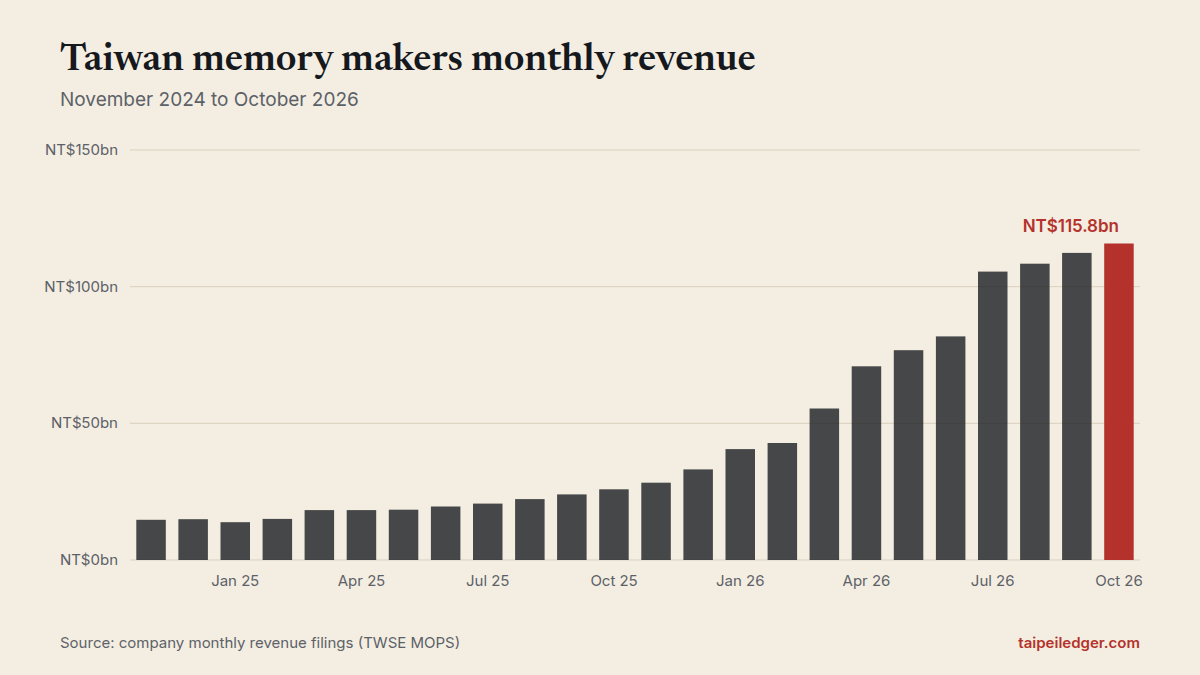
The makers' own revenue tells the same story from the other side of the invoice. The 4 memory and storage companies tracked by Taipei Ledger, Nanya Technology (2408), Winbond (2344), Phison (8299), Macronix (2337), together filed revenue of NT$115.8bn for October 2026, up 347.9% on a year earlier. The 7 board and materials makers filed NT$98.7bn in the same month, up 80.7%. Nanya Technology president Lee Pei-ing told investors that "DRAM is still in very tight supply", and said third-quarter profit rose mainly because higher contract prices took effect in July, after long-term agreements expired at the end of June. 7
For memory, more increases are forecast. TrendForce projected on 30 September that conventional DRAM contract prices would rise 10–15% quarter on quarter in 4Q26 and NAND Flash contract prices 15–20%. It said the pace of DRAM increases is moderating, and that enterprise SSDs are the only category where price growth is expected to accelerate. It also noted that improving server CPU availability has led cloud providers and server makers to raise their memory orders. 6
Waiting times are the harder cost to plan around. Distributor Fusion Worldwide reported that Texas Instruments' quoted 12–16 week lead times were stretching closer to six months, with some customers seeing 52+ weeks, its MCUs at 40+ weeks, and another 10–15% price increase expected in October. On processors, it said Intel server CPU constraints extend into 2027, and that AMD EPYC pricing was expected to rise 10%+ in the fourth quarter, with lead times from three weeks to six months. It said Micron SSD pricing was up 20–25% on average for October EMEA shipments. 4
Circuit boards and substrates face a supply squeeze of their own. Unimicron chairman S.C. Chien told the Taiwan Printed Circuit Association show on October 20 that lead times had lengthened for more than 80% of equipment, with some key equipment at 30 months. He said low-CTE glass fiber cloth, copper-clad laminates and ABF were particularly tight, and that critical materials could face a 20% supply shortfall in 2027. Fusion Worldwide said PCB lead times had reportedly doubled over the past year. 84
Two dates are already on the calendar. DGBAS is due to publish its next price release on December 8, 2026. Nanya says equipment installation at its new 5A fab is scheduled to begin in the first quarter of 2027. 27
Sources: 2. DGBAS: The price indices for October 2026 (English news release) · 4. Fusion Worldwide: The Greensheet, October 2026 (distributor market report) · 6. AI Server Demand Sustains Memory Contract Price Increases in 4Q26, While Consumer-Side Pressure Pers · 7. Nanya Technology expects DRAM prices, margins to rise in Q4 - Focus Taiwan · 8. TrendForce: Unimicron warns of IC substrate crunch (20 October 2026)